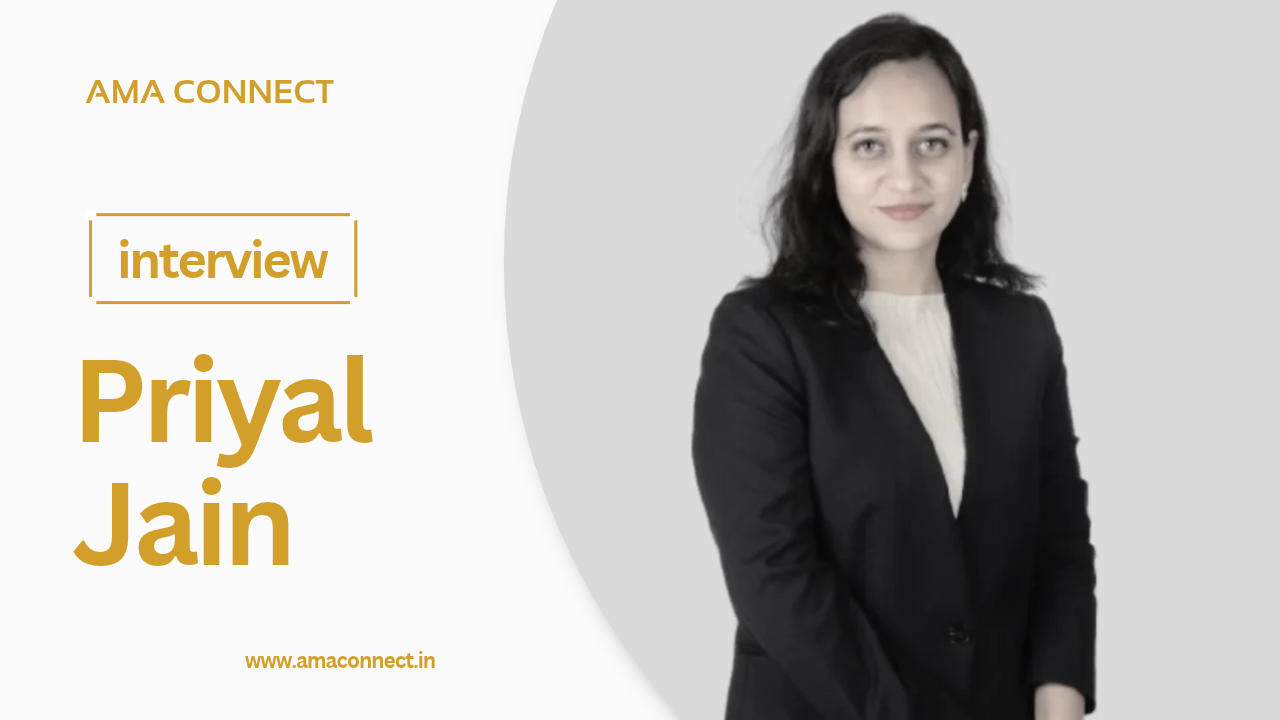
In Conversation with Priyal Jain
Principal Associate at JSA Advocates & Solicitors
1. You have built a decade-long career in corporate transactions, regulatory advisory, and deal execution. Could you take us through your professional journey, the experiences that shaped your expertise, and what inspired you to specialize in corporate law?
Priyal Jain:
My journey in corporate law has been shaped by nearly a decade of transactional work, regulatory advisory, and exposure to complex, cross-border arrangements.
I graduated from NLIU Bhopal in 2016 and moved alone to Delhi to build my career from the ground up, beginning at Bharucha & Partners. That early stint helped me learn the ropes of corporate transactions and commercial advisory and quickly taught me that legal advice cannot operate in isolation; it must walk hand in hand with commercial objectives. In 2018 I joined JSA Advocates & Solicitors, where I have spent the greater part of my career and currently serve as Principal Associate. Over this period I have worked across M&A, private equity and venture capital investments, joint ventures, business and asset transfers, corporate restructuring and NCLT matters, as well as cross-border transactions and corporate governance. Parallel to this, I have built substantial experience in commercial contracting spanning technology, services, hospitality, employment, and real estate.
A significant portion of my practice involves advising multinational and large Indian clients on the regulatory overlay of their operations: Companies Act, FEMA, RBI, FCRA, data privacy, and sector-specific frameworks. I have also handled high-value mandates involving overseas investors, acquisitions of Indian businesses, shareholder exits, and intricate investment structures, often requiring coordination across multiple jurisdictions and stakeholders. What has most shaped my approach is the opportunity to engage with matters across the full lifecycle, from structuring and negotiating a transaction at the outset to managing regulatory, contractual, and governance issues as the business evolves. This has allowed me to see both the forest and the trees and to strike the right balance between legal risk and commercial goals.
What inspired me to specialize in corporate law was the realization that it sits at the true intersection of business strategy and legal architecture. My father is a chartered accountant and my sister an MBA, so dinner table conversations at home often revolved around balance sheets, market trends, and how companies were run. Later, watching my life partner, who is also a corporate lawyer, navigate complex legal challenges and seeing how law both frames and enables commercial outcomes, made it clear that this was the field where problem solving, structure, and real-world impact come together.
2. Having worked on complex, multi-jurisdictional transactions, including a notable USD 500 million fundraise, what are the most challenging aspects of executing high-value deals? How do you ensure that legal strategy aligns with commercial objectives while managing transaction risks?
Priyal Jain:
Having worked on complex, high-value transactions, including a USD 500 million investment by an overseas fund into a leading Indian real estate company, which involved drafting and negotiating shareholders’ and operating agreements, development and project management agreements, and several ancillary documents, I believe the biggest challenge in executing such deals is balancing legal protection with commercial practicality. In transactions of this scale, there are multiple stakeholders, competing interests, regulatory considerations, and timelines, and the challenge is to ensure that all these aspects come together without losing sight of the underlying business objective. I typically categorize issues as must-haves, good-to-haves, and negotiable. Must-haves are those critical to the transaction structure, regulatory compliance, or protection of the client’s core interests. Good-to-have protections can be negotiated depending on the commercial context, while other points may be accepted where the risk is manageable.
This prioritization becomes particularly important during negotiations. Not every legal risk needs to become a deal breaker, and not every contractual protection needs to be pursued at the cost of the larger transaction. This approach is particularly important in multi-jurisdictional transactions, where there are multiple stakeholders, regulatory considerations, and tight timelines. I believe a corporate lawyer needs to function as a business enabler and risk manager, rather than simply identifying legal issues. My objective is to provide the client with a clear understanding of the risks, the available options, and their commercial implications so that decisions can be made consciously and efficiently. A successful transaction is not necessarily one in which every legal point is negotiated in the client's favour; it is one in which the client's key interests are protected, material risks are appropriately managed, and the commercial objective is achieved.
3. In M&A and Private Equity transactions, due diligence, structuring, and negotiations play a critical role. From your experience, what are the key legal and commercial considerations that can make or break a transaction, and how can lawyers contribute beyond identifying risks?
Priyal Jain:
In M&A and private equity transactions, three elements consistently decide outcomes: the quality of due diligence, the robustness of the structure, and the precision of negotiation and documentation.
Due diligence is far more than identifying red flags. The real value lies in quantifying their commercial impact, whether title defects, contingent liabilities, regulatory non-compliance under FEMA or the Companies Act, change of control triggers, data privacy exposures under the Digital Personal Data Protection Act, 2023, or labour and real estate issues. Equally critical is deciding how those issues should be handled: whether they are deal breakers that must be resolved as conditions precedent before closing or can be managed as conditions subsequent with appropriate protections such as escrow, indemnity, price adjustment, or post-closing covenants. Incomplete diligence or incorrect classification of issues as CP versus CS often leads to post-closing surprises that destroy value or derail the deal.
Structuring is the next decisive layer. Cross-border investments, joint ventures, slump sales, asset transfers, and group restructurings must simultaneously satisfy FEMA, the Companies Act, tax efficiency, and the parties’ commercial objectives around control, exit rights, funding mechanisms, and governance. A structure that looks elegant on paper but is difficult to implement or exit frequently collapses under regulatory scrutiny or practical friction. The key questions are straightforward: Can the foreign investor bring in and repatriate funds smoothly? Will governance rights survive future rounds? Is the exit path whether IPO, secondary sale, or put/call, both legally and commercially viable? Getting this balance right is what separates a transaction that closes cleanly from one that gets stuck in approvals or post closing disputes.
Finally, negotiation and documentation demand absolute precision. Indemnity caps, baskets, survival periods, representations and warranties, particularly around title and regulatory compliance conditions precedent, and post-closing covenants must be drafted with zero ambiguity. Subjective language is an invitation to future disputes. Beyond standard protective clauses, the real skill lies in calibrating them to the specific risk profile of the deal, tightening where diligence has revealed material exposures, and remaining commercially reasonable where the risk is remote. The documentation must accurately capture the commercial understanding reached at the table so that what was agreed orally is enforceable on paper without room for reinterpretation.
Lawyers add the most value when they move beyond flagging risks to designing practical, risk-calibrated solutions that enable the business decision and protect value through closing and beyond. This means translating commercial understanding into tightly drafted clauses that leave no room for interpretive disputes.
“Measure twice, cut once." In deal making, that second measure of commercial impact, regulatory feasibility, and precise documentation is what ultimately protects value and enables the transaction to succeed.
4. With evolving regulations under the Digital Personal Data Protection Act, foreign exchange laws, and the Companies Act, how are regulatory changes influencing corporate transactions in India? What should businesses and legal professionals prioritize to navigate this evolving compliance landscape?
Priyal Jain:
Regulatory changes under the Digital Personal Data Protection Act, 2023 (DPDP Act), foreign exchange laws (primarily FEMA), and the Companies Act, 2013 are fundamentally reshaping how corporate transactions are structured, negotiated, and closed in India.
The DPDP Act has elevated data privacy from a compliance checkbox to a material commercial factor. In mergers, acquisitions, and private equity investments—particularly in technology, healthcare, e-commerce, and consumer-facing businesses personal data is now treated as both an asset and a potential liability. Due diligence routinely includes data mapping, assessment of consent frameworks, and evaluation of cross-border transfer mechanisms. Gaps in these areas can affect valuation, indemnity negotiations, and, in some cases, the viability of the transaction itself.
Simultaneously, FEMA continues to shape cross-border investments, exits, and joint ventures. Evolving reporting requirements, stricter scrutiny of fund flows, and the practical realities of compounding proceedings mean that even routine capital raises or secondary sales can face delays if the structure is not carefully calibrated from the outset. The Companies Act, with its frequent amendments and heightened governance expectations, has similarly increased the documentation and approval burden around schemes of arrangement, mergers, and stake acquisitions.
Compliance has therefore moved from a post deal checklist to a core commercial consideration. For businesses, the priority should be to treat compliance as an ongoing discipline rather than a pre deal clean up exercise. For legal professionals, the focus should be on identifying regulatory issues early, building realistic approval timelines into the transaction calendar, allocating regulatory risk precisely in the documents through targeted representations, specific indemnities and conditions precedent, and staying continuously updated, because the law in these areas is changing faster than ever.
As the proverb goes, “A stitch in time saves nine.” A compliance gap addressed early costs little, the same gap discovered during diligence or after closing can delay the deal, erode value, or derail the transaction entirely.
5. Joint Venture Structuring and cross-border transactions often involve multiple stakeholders, jurisdictions, and competing commercial interests. What are the critical legal considerations in structuring such transactions, and what lessons have your professional experiences taught you about managing complex negotiations?
Priyal Jain:
In my experience, a joint venture or cross border transaction sits at the intersection of law, commerce, and human dynamics. So the first legal consideration is getting the structure right. Whether to use an Indian company, an LLP or an offshore holding entity depends on foreign exchange rules, sectoral caps and approval routes, tax treaty positions, and how easily funds can be brought in and taken out. Next comes governance: board composition, reserved matters, quorum and deadlock resolution. Everyone agrees on these in initial phase, but they really matter when the partners disagree. Exit rights are equally critical. Put and call options, drag and tag rights, and rights of first refusal must be drafted with Indian law in mind, particularly the pricing guidelines under FEMA, which do not allow a foreign investor an assured return. Finally, the choice of governing law, seat of arbitration and enforceability of awards in India, together with competition, intellectual property and data considerations, must be addressed upfront rather than left for later.
On negotiations, the biggest lesson I have learnt is to understand what each party truly needs, as opposed to what it is asking for. Once you know that, most deadlocks can be resolved through structure rather than confrontation, for example an earn out instead of a price fight, or a phased exit instead of an all or nothing option. One matter that taught me this was supporting a Fortune 500 company in its exit from an Indian joint venture, which demanded careful navigation of Indian corporate and foreign exchange laws, precise exit documentation and constant stakeholder management. I have also learnt the value of patience and preparation. Cultural differences, time zones and internal approval layers on both sides can slow things down, and a lawyer who keeps the process moving calmly, with a clear issues list and a realistic timeline, earns the trust of everyone at the table.
As the proverb goes, “If you want to go fast, go alone; if you want to go far, go together.” A joint venture is, by definition, a decision to go far together, and the documents should reflect a partnership both sides can live with. And as another old saying reminds us, “Good fences make good neighbours”, accordingly, clear governance and exit provisions are not a sign of mistrust, they are what allow the partners to keep working together when commercial interests eventually diverge.
6. With technology reshaping business models and legal practice, how are emerging technologies influencing commercial contracting, transaction execution, and regulatory advisory? What opportunities and challenges do you foresee for corporate lawyers in the coming years?
Priyal Jain:
Emerging technologies are reshaping commercial contracting, transaction execution and regulatory advisory in tangible ways. When I was in law school, we practically lived in the library, poring over books and case laws, today, tools like Manupatra and SCC Online take me straight to the relevant judgments in a click. AI powered tools now assist with contract review, risk analysis, clause suggestions and document hygiene checks, and tools such as Litera help with proofreading and document hygiene, significantly speeding up the first level review of standard agreements. In transaction execution, technology helps manage large volumes of due diligence documents, track closing checklists and flag inconsistencies faster than manual processes alone. On the regulatory side, tools that monitor legislative updates and map compliance requirements are becoming useful supplements to traditional research. I see this as a big opportunity for corporate lawyers. When technology takes over the routine work, lawyers can spend more time on what clients truly value: judgement, strategy, negotiation and commercial insight.
That said, while AI is effective for summarising documents and generating basic drafts, it is not always accurate in legal research and can produce incomplete or incorrect advice. Complex drafting, especially in cross border deals, joint ventures or high value M&A, still requires human judgment grounded in experience, commercial context and an understanding of how clauses will actually operate in practice. AI tools can be confidently wrong, so every output must be verified, and client confidentiality and data security must never be compromised. There is also a risk that young lawyers miss out on the foundational learning that comes from reading documents line by line, and firms will need to think carefully about how they train the next generation.
“A tool is only as good as the hand that wields it.” Technology may transform how legal work is done, but its value ultimately depends on the lawyer using it. The lawyers who will thrive are those who embrace technology without losing sight of the judgment, commercial instinct and responsibility that sit at the heart of good legal advice.
7. For law students and young professionals aspiring to pursue M&A, Private Equity, and corporate transactions, what skills, practical experiences, and professional habits would you recommend developing? What advice would you offer to those seeking to become commercially astute and effective corporate lawyers?
Priyal Jain:
For law students and young professionals aspiring to pursue M&A, private equity and corporate transactions, the first skill I would recommend is a strong command of the fundamentals: contract law, the Companies Act, foreign exchange laws and securities regulations. Deals change, but these foundations stay constant. Equally important is drafting. Learn to write clearly and precisely, because in a transaction document every word can carry commercial consequences.
On practical experience, I would encourage students to take internships seriously, sit through negotiations whenever possible, and volunteer for due diligence. Diligence can feel tedious, but it is where you truly learn how a business works and where risk actually sits. For young associates, the focus should not be on simply finishing the assigned work. Read every transaction document from start to finish, not just the clauses you have been asked to draft. Spend time understanding why a particular structure was chosen, how the clauses interact, and what commercial outcome the language is designed to achieve. Interpretation and conceptual clarity matter far more than speed of delivery in the early years.
“Rome was not built in a day.” A successful career in corporate law is built one transaction, one lesson and one late night at a time, and consistency will always take you further than shortcuts. To become commercially astute, think like the client. Read the financial press, understand how businesses make money, and ask what the client is really trying to achieve before deciding how to protect it. In my own practice. Build habits of discipline: double check your work, keep a running issues list, respond on time, and own your mistakes. Finally, stay curious and keep sharing what you learn, I firmly believe that knowledge shared is knowledge squared.